
Model example · fictional brief and source documents
Company earnings review before an acquisition
From reported results to repeatable earnings.
Go to the conclusion Open the workbook and supporting files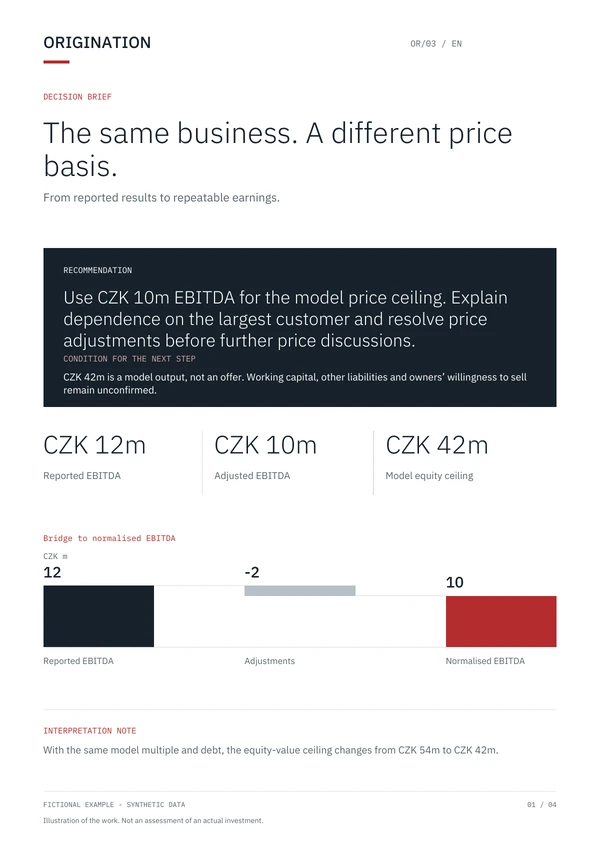
How much of reported profit belongs to normal operations?
Use CZK 10m EBITDA for the model price ceiling. Explain dependence on the largest customer and resolve price adjustments before further price discussions.
- The decisive finding
- A one-off gain on equipment disposal increased reported EBITDA by CZK 2m. Adjusted operating earnings are below the previous year.
- Impact
- With the same model multiple and debt, the equity-value ceiling changes from CZK 54m to CZK 42m.
- The remaining condition
- CZK 42m is a model output, not an offer. Working capital, other liabilities and owners’ willingness to sell remain unconfirmed.
Model · CZK m
Model equity value ceiling before other price adjustments. The multiple is a hypothetical buyer’s rule.
Evidence and calculations
Fictional demonstration with synthetic source documents. Company A makes industrial components. Comparing synthetic statements with ledger detail reveals a one-off gain. The hypothetical buyer chose a 6.0 multiple; this is neither a market valuation nor a real business offered for sale.
| Year | Revenue | Reported EBITDA | One-off adjustment | Adjusted EBITDA | Adjusted margin | Source |
|---|---|---|---|---|---|---|
| 2023 | CZK 104m | CZK 9.2m | CZK 0m | CZK 9.2m | 8.85% | C-S01 |
| 2024 | CZK 112m | CZK 10.5m | CZK 0m | CZK 10.5m | 9.38% | C-S01 |
| 2025 | CZK 120m | CZK 12m | CZK -2m | CZK 10m | 8.33% | C-S01; C-S02 |
Records shown: 3
C-F01 / Calculation
Two million did not come from normal production.
The ledger shows equipment-disposal proceeds of CZK 3m and a carrying amount of CZK 1m. The net effect included in reported EBITDA is +CZK 2m; the model excludes it as non-recurring.
C-S02 · Rows L01–L02 / equipment disposal ↓C-F02 / Calculation
Revenue growth masks a weaker margin.
Revenue rises from CZK 112m to CZK 120m, but EBITDA after the one-off adjustment falls from CZK 10.5m to CZK 10m. Adjusted margin changes from 9.38% to 8.33%. Explaining it requires a price, volume and cost bridge.
C-S01 · Table 1 / 2024–2025; adjustment C-S02 ↓C-F03 / Calculation
The same multiple gives a lower price ceiling.
12 × 6 − 18 = CZK 54m before adjustment; 10 × 6 − 18 = CZK 42m after it. The CZK 12m difference comes solely from the earnings base. The multiple is the model buyer’s rule, not a market benchmark.
C-S04 · Section 2 / price bridge ↓C-F04 / Open question
Net debt must be separated from other adjustments.
The model lists bank debt of 22 and cash of CZK 4m: net debt of CZK 18m. It lacks a complete lease schedule, other debt-like items and target working capital. The bridge is therefore not the final purchase price.
C-S03 · Section 2 / debt and cash ↓C-F05 / Analyst interpretation
Ownership percentage does not determine signing authority.
The synthetic profile lists Owner A at 60% and Owner B at 40%. Transaction discussions require both under the model brief. Shareholdings alone establish neither authority to sign a sale nor consent to it.
C-S03 · Section 1 / ownership and authority ↓C-F06 / Open question
A third of revenue needs a separate explanation.
The largest customer represents 35% of revenue, or CZK 42m in the model. Its contract, margin and termination terms are missing. The percentage alone is not enough to accept or reject the opportunity.
C-S01 · Section 2 / customers ↓Fictional working example · version 1.0
Recalculate the conclusion.
The workbook includes inputs, formulas, six findings and management questions. Each material figure is linked to its synthetic source.
No registration. The ZIP includes the workbook, original PDF, CSV, source extracts and review instructions. Amounts are in CZK millions.
Review status: no financial reviewer has been assigned. This example has not received professional approval.
Using the workbook and handing it over for review
- Save your own copy. Change only the marked inputs; formulas refer to those inputs. The original PDF and CSV remain a snapshot of the initial case.
- Reassess the findings and questions after changing inputs. Missing working capital and other liabilities are not zero balances.
- A second person independently recalculates the EBITDA adjustment and price bridge, checks sources and logs comments. The preparer records corrections and their impact.
- The reviewer records the exact version, scope, date, review outcome and unresolved points. Approval requires explicit sign-off on that version, with all blocking comments resolved.
Method references
The distinction between sustainable earnings, net debt and working capital follows the financial due diligence descriptions from EY and PwC. Input traceability, formula checks and version history draw on ICAEW spreadsheet principles and its spreadsheet review guidance.
This is our application of those principles. These references do not validate the fictional figures, the assumed multiple or our work.
Financial working schedules
The companion workbook separates the original model into an EBITDA bridge, working capital, and debt and cash. Findings identify evidence, possible implications and the next question to verify.
Fictional teaching example. Monthly working-capital data is missing and the input cells remain blank. CZK 42m is a partial model bridge before further adjustments, not a final purchase price.
What can be recalculated and what remains open
- Original EBITDA of 12 − (3 − 1) = CZK 10m links to C-S01 and C-S02. The original PDF, CSV and handover workbook remain available above.
- The blank monthly schedule calculates only when consistent periods, amounts and evidence are supplied. Missing is not zero; the average is not treated as an agreed working-capital target.
- Bank debt of CZK 22m and reported cash of CZK 4m in C-S03 produce partial net debt of CZK 18m. Other items and cash availability need classification and evidence.
- Reassess conclusions and finding narratives after editing inputs. No qualified reviewer has been assigned; calculation does not constitute professional approval.
The financial topics and boundaries follow the descriptions from EY and PwC. PwC on closing accounts emphasises contractual definitions and avoiding double counting. Scope and classification depend on the transaction; these references do not verify our capacity or approve this example.
Supporting source material
We created these documents for this fictional scenario. They support findings within the example and do not establish facts about a real company, investor or property.
C-S01 / 2026-09-01Synthetic trading and customer summary
Synthetic document · Table 1 and section 2
Synthetic document. Company A; amounts in CZK m. 2023: revenue 104, EBITDA 9.2. 2024: revenue 112, EBITDA 10.5. 2025: revenue 120, EBITDA 12. No one-off adjustments are listed in the model for 2023 or 2024. EBITDA 2025 includes the net equipment-disposal gain in C-S02. The largest customer represents 35% of 2025 revenue. Its contract, customer margin and termination terms are not attached.
C-S02 / 2026-09-01Synthetic ledger detail of the one-off item
Synthetic document · Rows L01–L02
Synthetic document. Ledger detail for model year 2025: L01, disposal of retired equipment, proceeds CZK 3m. L02, derecognition of the same equipment, carrying amount charged to costs CZK 1m. The net CZK 2m gain is included in reported EBITDA of CZK 12m under the synthetic management summary. Disposal is outside normal component manufacturing. This model contains no other EBITDA adjustment or replacement investment for the equipment.
C-S03 / 2026-09-01Synthetic ownership and financing profile
Synthetic document · Sections 1–2
Synthetic document. Owner A: 60%; Owner B: 40%. The model brief requires both to participate in transaction discussions. This is not a registry extract and does not establish authority to sign a sale. Bank debt CZK 22m, cash CZK 4m. A complete lease schedule, other debt-like items and target working capital are missing. Owners’ willingness to sell is unconfirmed and no contact has taken place.
C-S04 / 2026-09-01Synthetic buyer rule and price bridge
Synthetic document · Sections 1–2
Synthetic document. The model buyer applies a ceiling of 6.0× adjusted EBITDA. The multiple is not market-derived. Inputs from C-S01 through C-S03: reported EBITDA 12, one-off adjustment −2, adjusted EBITDA 10, net debt 22 − 4 = CZK 18m. Before adjustment: enterprise value 72 and equity value 54. After adjustment: enterprise value 60 and equity value 42. Working capital, other price items and transaction expenses are considered separately. This is not a price offer.
Checks before the next step
- 01
Explain margin trends and customer dependence.
Owner: Management and financial analyst
Evidence to close: Price, volume and cost bridge; largest-customer contract and margin; recurring and one-off items separated.
- 02
Complete the price bridge.
Owner: Finance and legal teams
Evidence to close: Current debt, cash, leases, other liabilities and agreed working capital, with evidence for every adjustment.
- 03
Approve an approach to both owners.
Owner: Buyer and engagement lead
Evidence to close: Evidenced ownership and authority, an approved message and questions on willingness, timing and price expectations.
Discuss your brief
We will discuss your criteria and available evidence, then propose specific deliverables, timing and a fixed fee. The first consultation is free.